Five reasons to turn super into income
You’ve spent years building your super—now it’s time to turn those savings into income. Here are some strategies to help keep your money working for you after you make the retirement leap.
A little about Joel
Joel is the Director, Retirement Solutions at Russell Investments. A Fellow of the Institute of Actuaries, he helps members and clients navigate complex challenges and has worn many hats across the superannuation and consulting businesses. Joel currently leads a program of work aimed at making continuous improvements to Russell Investments’ offer for members approaching, at, or in retirement.
Retirement changes not only how you spend your time but also where your income comes from. After years of relying on a salary or wage from employment, retirement opens the option to use your carefully accumulated super balance to fund your day-to-day life.
For many people, that will mean starting a retirement income stream, such as an account-based pension or a lifetime income product (sometimes called an annuity). Rather than thinking of super only as a nest egg to preserve, an income stream like this turns your savings into regular payments while keeping the rest of your money invested.
What suits you will depend on your circumstances, but here are some top reasons it may be worth starting an income stream from your super.
1. Receive tax-free income payments
For most people aged 60 or over, payments from a retirement income stream are generally tax-free. That can make an income stream a simple and tax-effective way to replace at least part of the employment income you were used to receiving. Your circumstances matter so it is important to understand the rules before deciding.
2. Pay less tax (nothing) on investment earnings
If you retire permanently at age 60 or later, or you reach age 65, you can generally access your super. This allows you to move eligible super savings into the retirement phase to support a pension, noting that investment earnings on those savings are generally tax free. That can make a significant difference compared with leaving the same money in an accumulation account, where investment earnings may still be taxed. Moving into a pension product means more of your investment earnings can either remain invested or used to fund your retirement lifestyle.
3. Keep your retirement savings invested
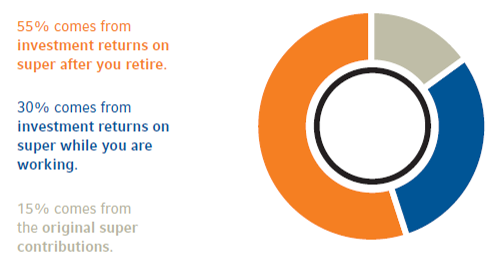
Starting a retirement income stream does not mean your super stops working. Your balance can remain invested even as you draw from it, giving it the opportunity to continue earning returns throughout retirement. In fact, the 15/30/55 rule suggests that as much as 55% of your potential retirement income can come from investment returns earned after you retire. That compares with 30% from returns earned during your working life, and just 15% from your original super contributions.
4. Retain flexibility over how you access your money
Retirement spending can vary from month to month. It may suit you to have regular fortnightly or monthly payments for living costs, but you may also need extra money from time to time for larger expense items like holidays or home repairs. A retirement income stream can give you flexibility around how much you draw, how often you receive payments and any additional lump sums you may need.
5. Some products may help with Age Pension eligibility
Your choice of income stream can affect the amount of government Age Pension you receive. Once you reach Age Pension age, your super is generally assessed under both the income and assets ‘means’ tests. For example, lifetime income products that meet certain rules are treated favourably under the means test which may result in high Age Pension entitlements. The outcome depends on the type of income stream, when it was purchased and your circumstances, so check the Services Australia rules before making a decision.
Put your super to work (and spend it, too!)
Moving from earning an income to drawing on your retirement savings can be a big transition. A retirement income stream can provide regular income for your lifestyle today while keeping the rest of your savings invested for the years ahead. If you plan to keep working, a transition to retirement income stream may also help you reduce your hours and supplement your income.
Your next step is to work out how much income you’ll need and which approach suits you: leave your super where it is, start an income stream, take a lump sum or combine these options. It’s important to consider the potential impact on tax, investment returns, fees and government benefits before making a decision.
General advice can help you understand your options, but it does not take your personal circumstances, goals or retirement needs into account. Personalised financial advice can help you apply those options to your situation – whether you need targeted help setting up a pension or transition-to-retirement strategy, or comprehensive advice that considers your full financial picture, including investments outside super. We can help with both.
You’ve spent years building your super. Now it’s time to put it to work for the retirement you want. Review your options, estimate your income needs and consider speaking with a financial adviser before deciding how to use your super.
Zest! recommends
Issued by Total Risk Management Pty Limited ABN 62 008 644 353, AFSL 238790 (TRM) as trustee of Russell Investments Master Trust ABN 89 384 753 567. Nationwide Super and Resource Super are Divisions of the Russell Investments Master Trust. The Product Disclosure Statement (‘PDS’), the Target Market Determinations and the Financial Services Guide can be obtained by phoning 1800 555 667 or by visiting russellinvestments.com.au, or for Nationwide Super by phoning 1800 025 241 or visiting nationwidesuper.com.au, or for Resource Super by phoning 1800 824 227 or by visiting resourcesuper.com.au. Any potential investor should consider the latest PDS in deciding whether to acquire, or to continue to hold, an investment in any Russell Investments product. Russell Investments Financial Solutions Pty Ltd ABN 84 010 799 041, AFSL 229850 (RIFS) is the provider of MyTracker and the financial product advice provided by GoalTracker Plus. General financial product advice is provided by RIFS or MUFG Retire360 Pty Limited (Retire360) ABN 36 105 811 836, AFSL 258145. Limited personal financial product advice is provided by Retire360 with the exception of GoalTracker Plus advice, which is provided by RIFS. Russell Investments Employee Benefits Pty Ltd (70 099 865 013) (RIEB) is the provider of the Super Tracker Mobile App.
This communication provides general information only and has not been prepared having regard to your objectives, financial situation or needs. Please note, errors may occur on occasion and if they do we will rectify them. If you identify an error, please let us know and we will rectify it. Before making an investment decision, you need to consider whether this information is appropriate to your objectives, financial situation and needs. If you'd like personal advice, we can refer you to the appropriate person. This information has been compiled from sources considered to be reliable but is not guaranteed. Past performance is not a reliable indicator of future performance. To the extent permitted by law, no liability is accepted for any loss or damage as a result of reliance on this information. This material does not constitute professional advice or opinion and is not intended to be used as the basis for making an investment decision. This work is copyright 2026. Apart from any use permitted under the Copyright Act 1968, no part may be reproduced by any process, nor may any other exclusive right be exercised, without the permission of Russell Investments.
On July 2, 2026, Russell Investments Group, Ltd. (“Russell Investments”) entered into a definitive agreement and plan of merger (the “Transaction”) pursuant to which Russell Investments will be acquired by a consortium led by B Capital Group Management, L.P. that includes California Public Employees Retirement System. The Transaction is expected to close by the end of Q1 2027, subject to the receipt of regulatory approvals and other customary closing conditions.