
Historically, markets have often rallied after midterm elections as the results reduce uncertainty. Russell Investments’ Sentiment Indicator shows that risk aversion declined by a standard deviation in the 180 days after midterms, while the S&P 500 rose by around 8% over the same period. Past performance does not guarantee future results.
Key takeaways:
- History suggests election nerves fade once the results are in, as markets typically rally post-midterms.
- Markets are likely to prove resilient across the main election scenarios.
- The data center debate could become a flashpoint for the AI investment buildout in 2027.
With the U.S. midterm elections three weeks away, investors are weighing the implications of a shift in control of Congress. President Trump is not on the ballot, but prediction markets put the probability of Democrats winning back one or both chambers at 90%, while a split Congress is priced at around 30%.
Balance of power: 2026 midterms
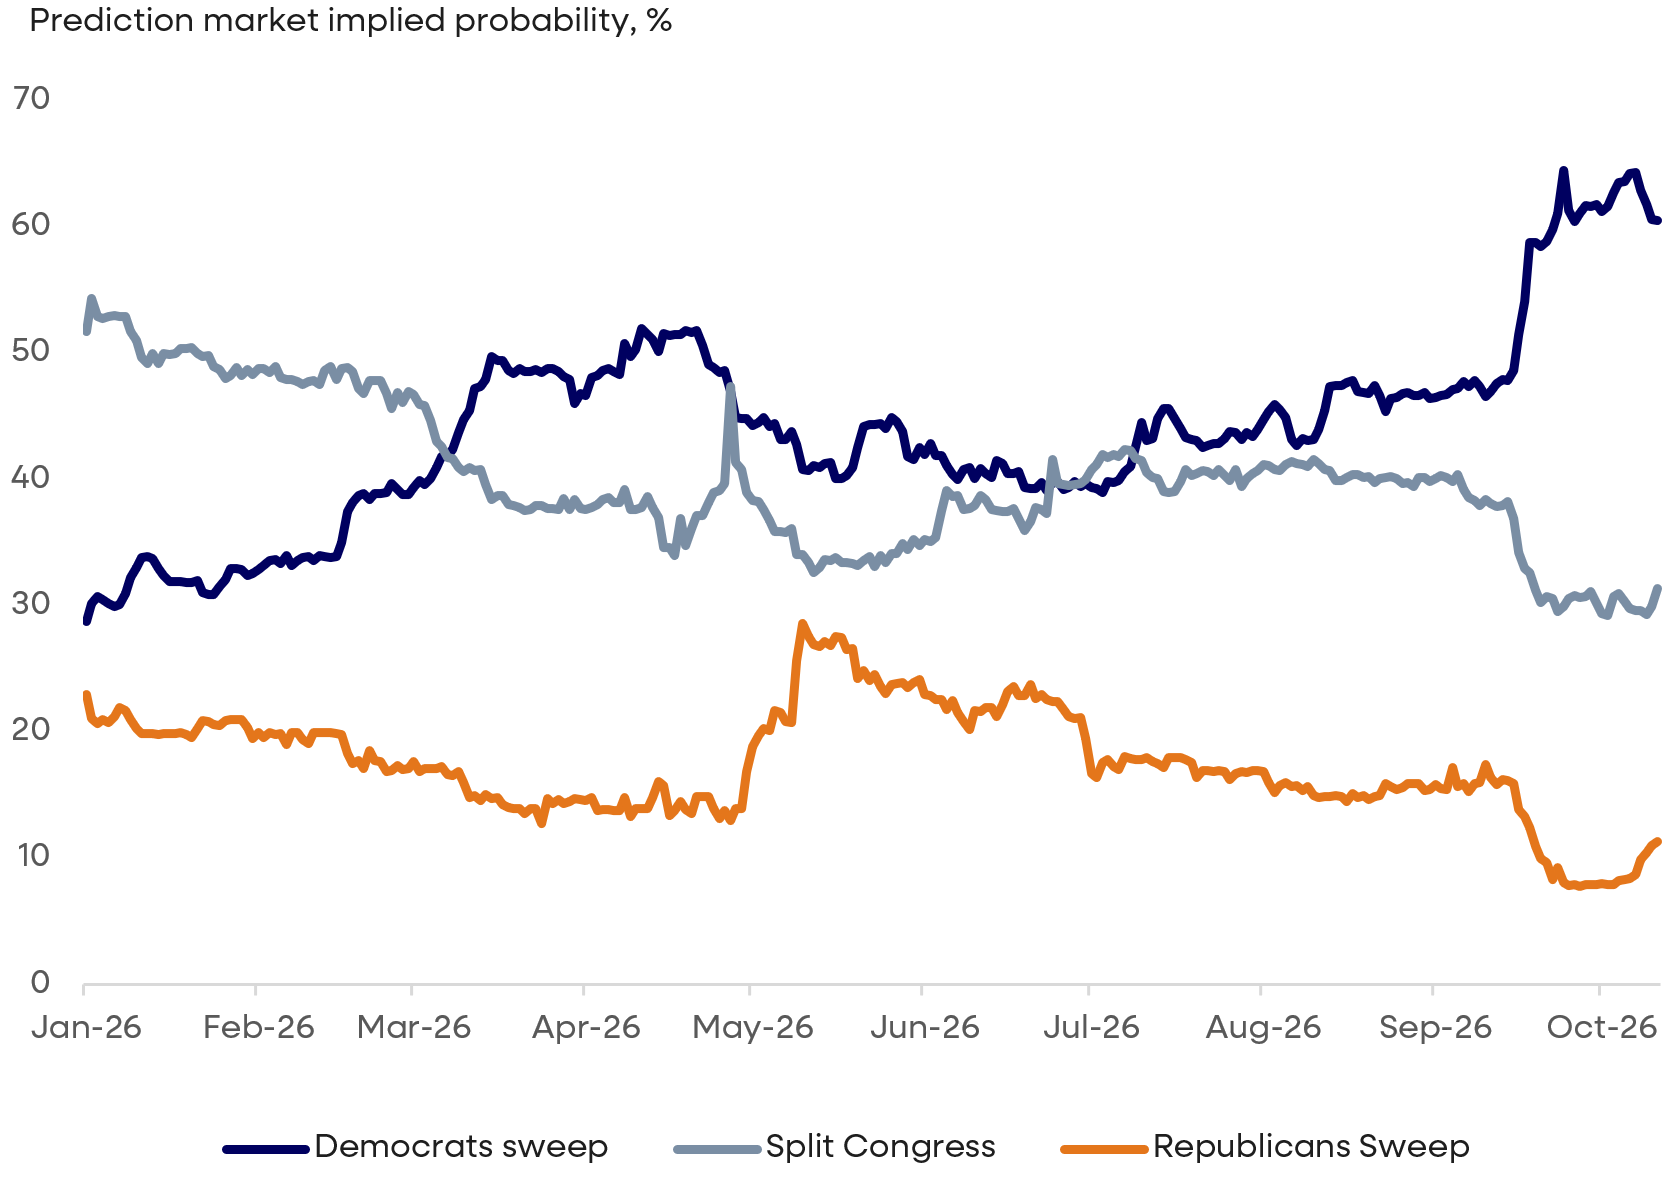
Source: Kalshi, Russell Investments. October 10, 2026.
For investors, the key question is how different outcomes could affect policy, which policies are likely to remain in place, and how they will ultimately impact the economy.
The good news is the economy has absorbed considerable uncertainty over the past 23 months, suggesting it is well placed to weather the election period. Despite stubborn inflation, U.S. growth has remained resilient, equities are near all-time highs and bond yields are near multi-decade highs.
Against this backdrop, this article examines the main election scenarios, their potential investment implications, and the policy issues to watch into 2027.
Investors faced large policy shifts during Trump 2.0
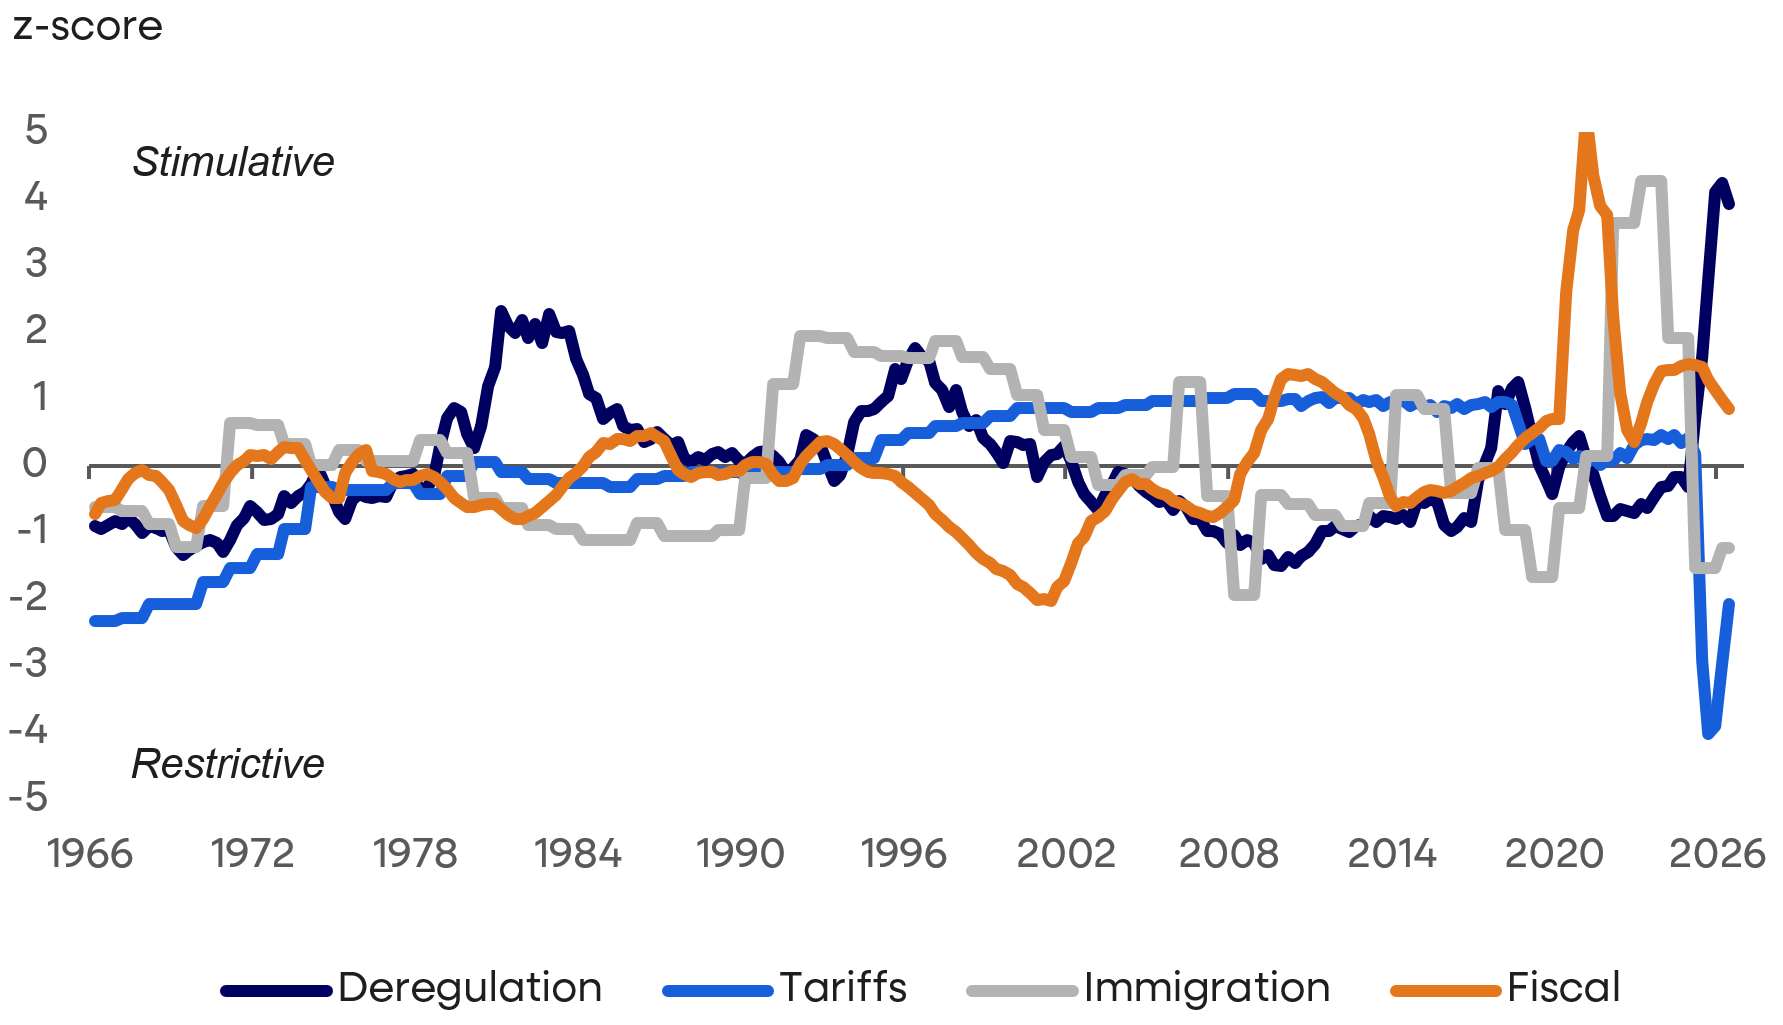
Source: Russell Investments. Data as of 2026:Q2. Deregulation is the Deregulation Enacted index from Iacoviello (2026). Fiscal is the budget deficit excluding automatic stabilizers from CBO (2025) with tariffs stripped out. Immigration is the contribution of immigration to population growth from CBO (2026). Tariffs are effective tariff rates from FRED.
Post-midterm confidence
Let’s first level set with what the long-term historical record says about midterms and markets. Elections do inject uncertainty and risk aversion into asset prices. Yet, once the results are known, that clarity often gives investors the confidence to step back into markets, driving a rally irrespective of which party wins.
According to Russell Investments’ Sentiment Indicator, in the 180-day period post-midterm elections, risk aversion has declined by a standard deviation and the S&P 500 Index, over the same period, has rallied around 8%.
Markets often rally on resolution of uncertainty
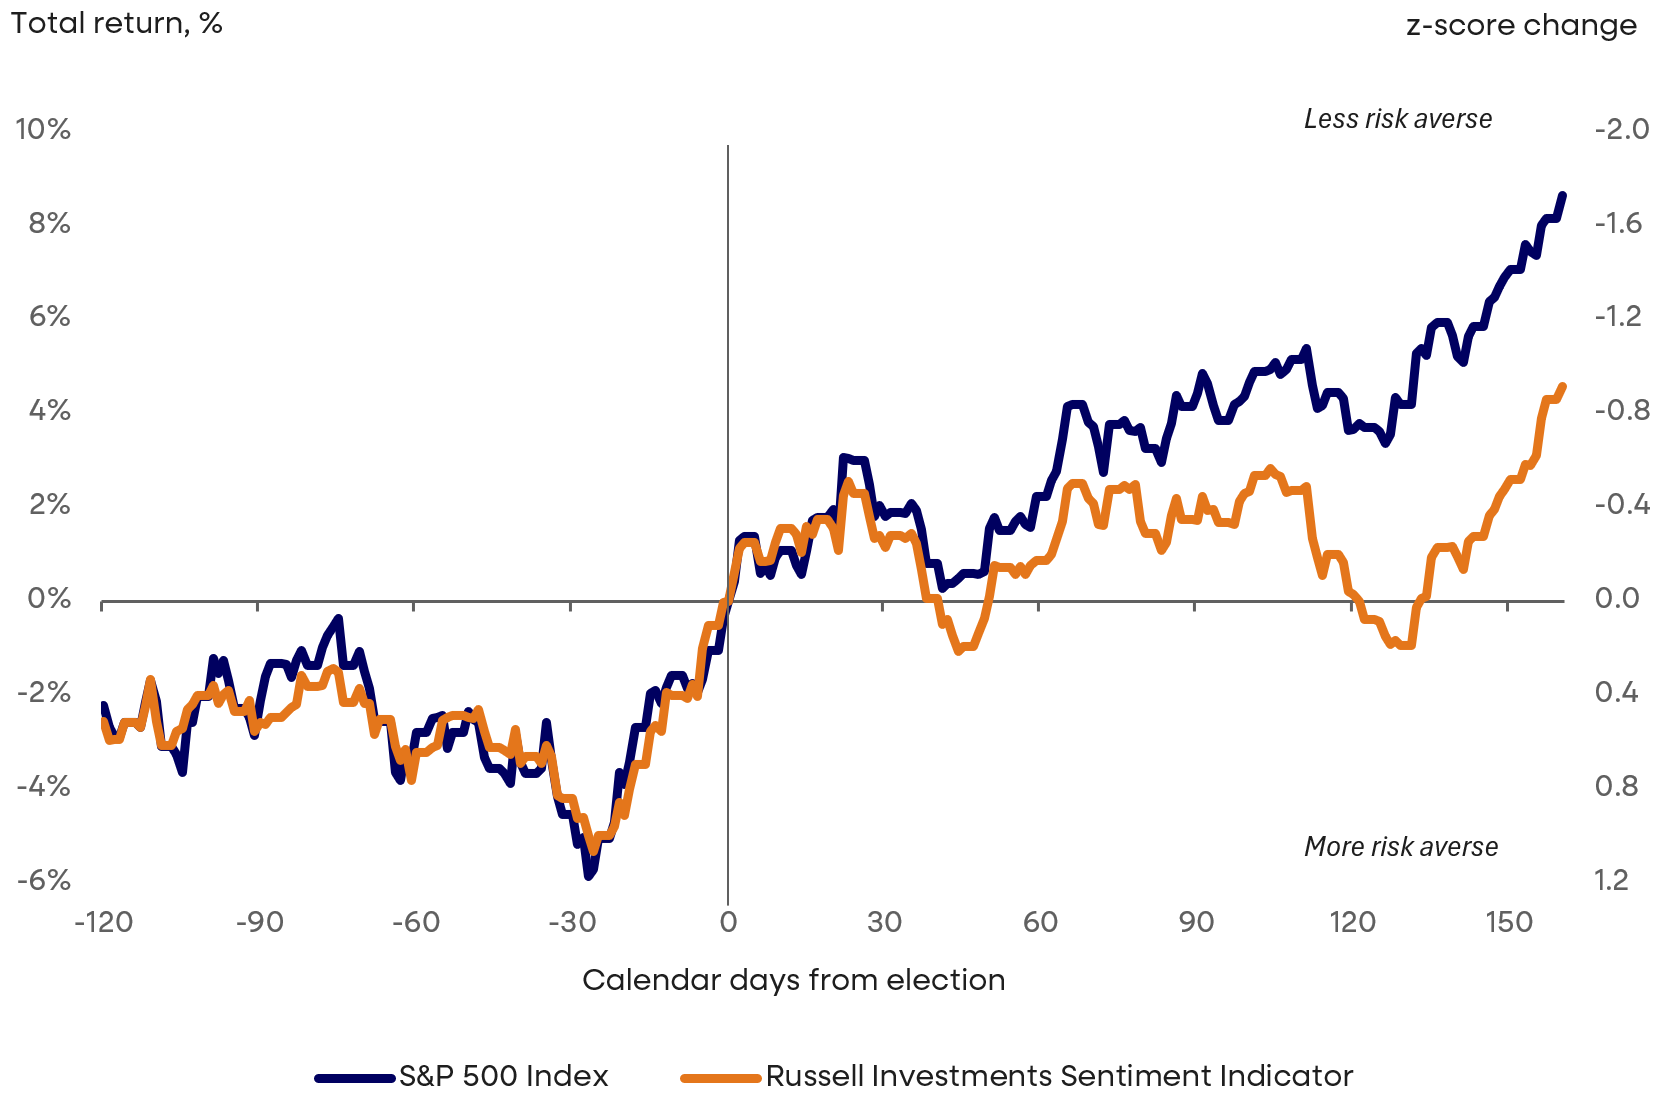
Source: Russell Investments, LSEG. Sample: all midterm elections 1998-2024.
Markets’ track record of post-election rebounds argues for strategic asset allocators to stay invested and for tactical asset allocators to be on the lookout for dip-buying opportunities if risk aversion spikes in the run-up to November 3.
Gridlock scenario preserves status quo
Will this midterm be the exception and see a post-election downturn? We don’t think so.
Prediction markets put the odds of the Democrats grabbing at least one chamber of Congress at 90%. Given the extreme polarization in U.S. politics today, a divided government would likely result in gridlock, with little or no material change to legislation for the next two years. The current status quo is favorable for Corporate America, including record low statutory tax rates.
Little common ground for policy compromise
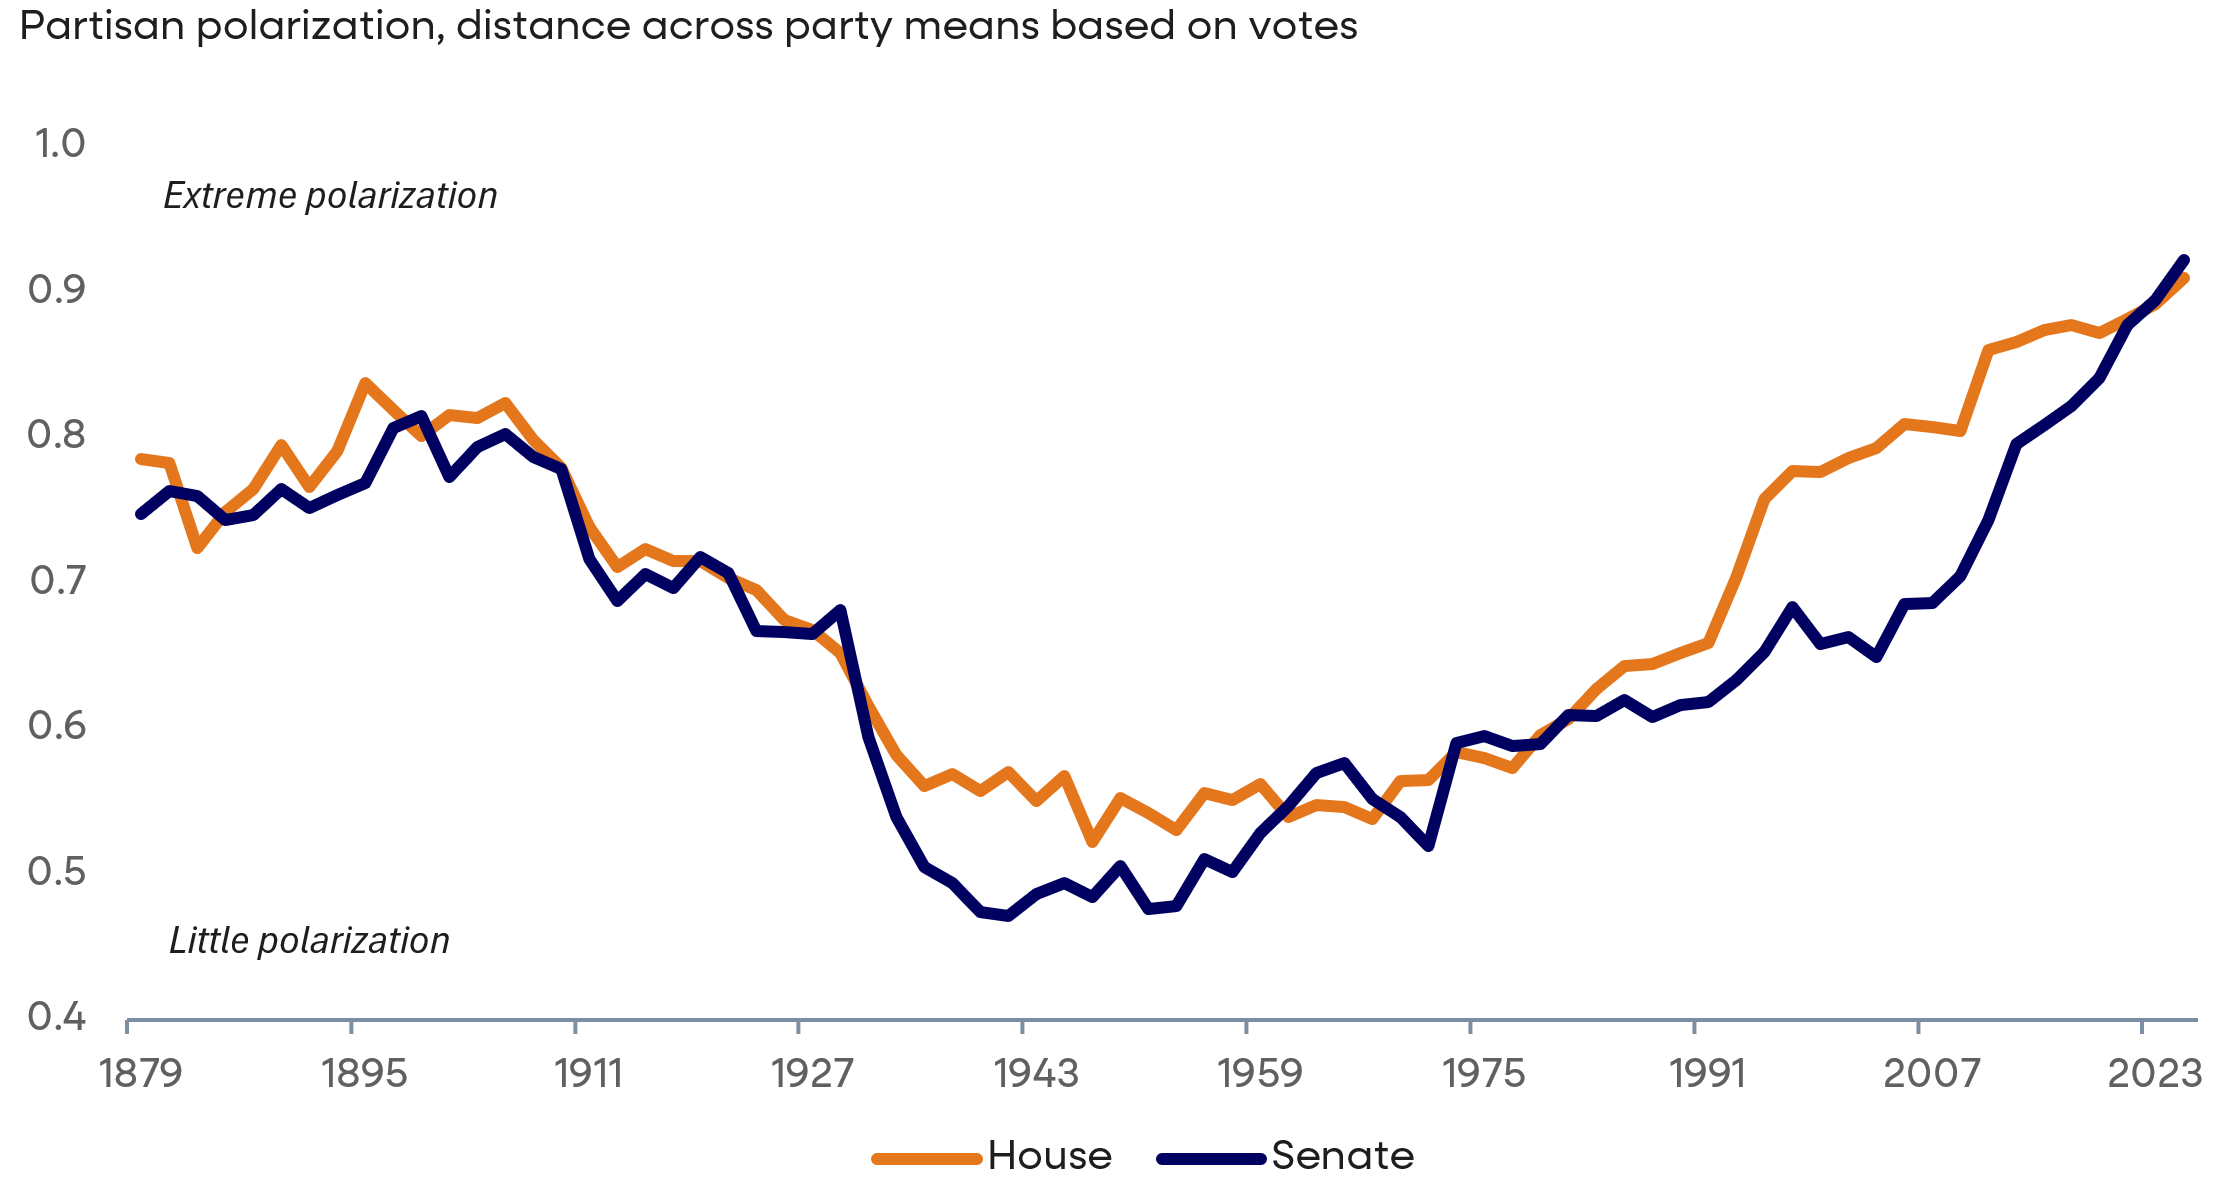
Source: UCLA Department of Political Science, Voteview, Russell Investments. Last updated: October 6, 2026.
Republican surprise scenario
Arguably the biggest risk for markets comes from the scenario that isn’t priced – i.e. if Republicans surprise and retain full control of the legislature. In this scenario, the economy is likely to be run hotter with some combination of the $5,000 Trump dividends to households, a federal gas tax holiday, and sector-specific aid packages (e.g. farmers) bolstering nominal growth, while leaving inflation sticky and interest rates higher for longer.
In the table below we summarize key policies and their expected fundamental impacts across election scenarios:
Table of 2026 midterm scenarios and implications
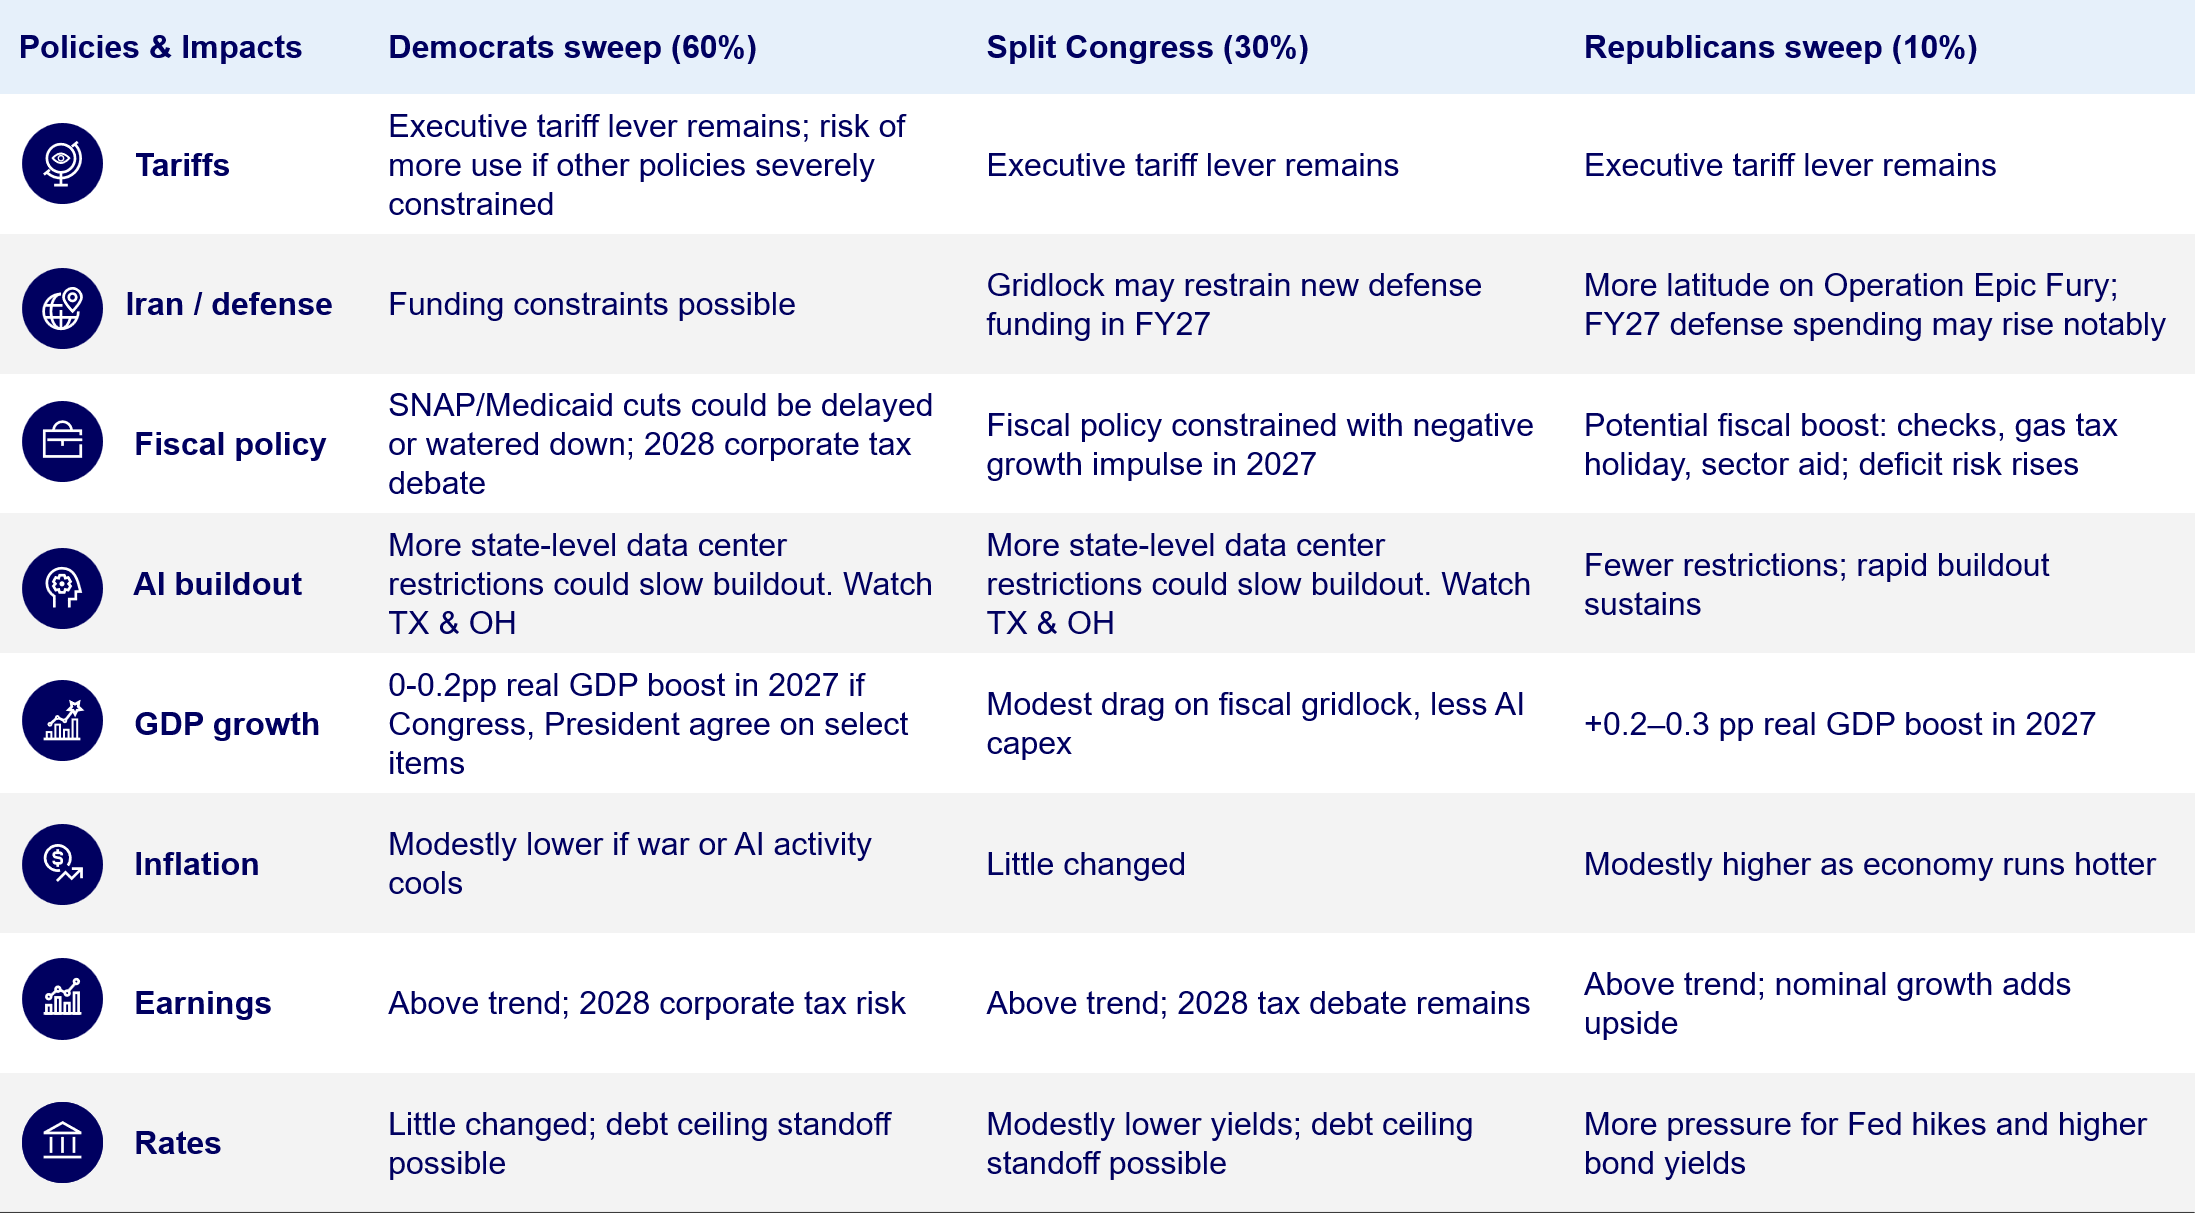
Source: Russell Investments. October 10, 2026. Directional scenario estimates.
What’s unlikely to change?
However, irrespective of the scenario, some policies are unlikely to change:
Tariffs: President Trump has substantial executive authority to impose tariffs. Effective tariff rates have stabilized in 2026 and have become less consequential for growth, inflation, and markets. Nevertheless, it’s possible he could use this lever more in 2027 if he feels constrained by a gridlocked or Democrat-controlled Congress.
Deregulation: The President has considerable control over how existing laws are carried out. He can appoint agency heads, direct their enforcement priorities, and ask independent agencies to submit draft regulations for White House review. While bolder unilateral actions risk legal challenge, the Supreme Court recently strengthened executive control over regulators (e.g. the FTC under Trump v. Slaughter, 2026).
Other policies like national defense lie principally within the executive branch but can be influenced indirectly by the legislature. For example, the White House sent a supplemental funding request to Congress in June to cover expenses that included its execution of the Iran War and replenishing munitions stockpiles.
The election could affect whether and on what terms Congress takes up these funding requests. Over time, its control of appropriations could also constrain the executive branch.
The data center debate
Meanwhile, the artificial intelligence buildout is a bipartisan focus for the midterms with data centers becoming increasingly unpopular among the American electorate. Electricity prices, water supply, noise, and the environment are among voter concerns.
These buildouts are a double-edged sword for local communities. While unpopular, the projects have also transformed state and local finances in parts of the country. For example, in Loudoun County, Virginia, data centers generated 38% of the revenue in its FY2026 budget, allowing the county to lower property taxes, build new schools, and improve emergency services.
Only one in six counties support new data centers
Net % of survey respondents who support a data center in their community
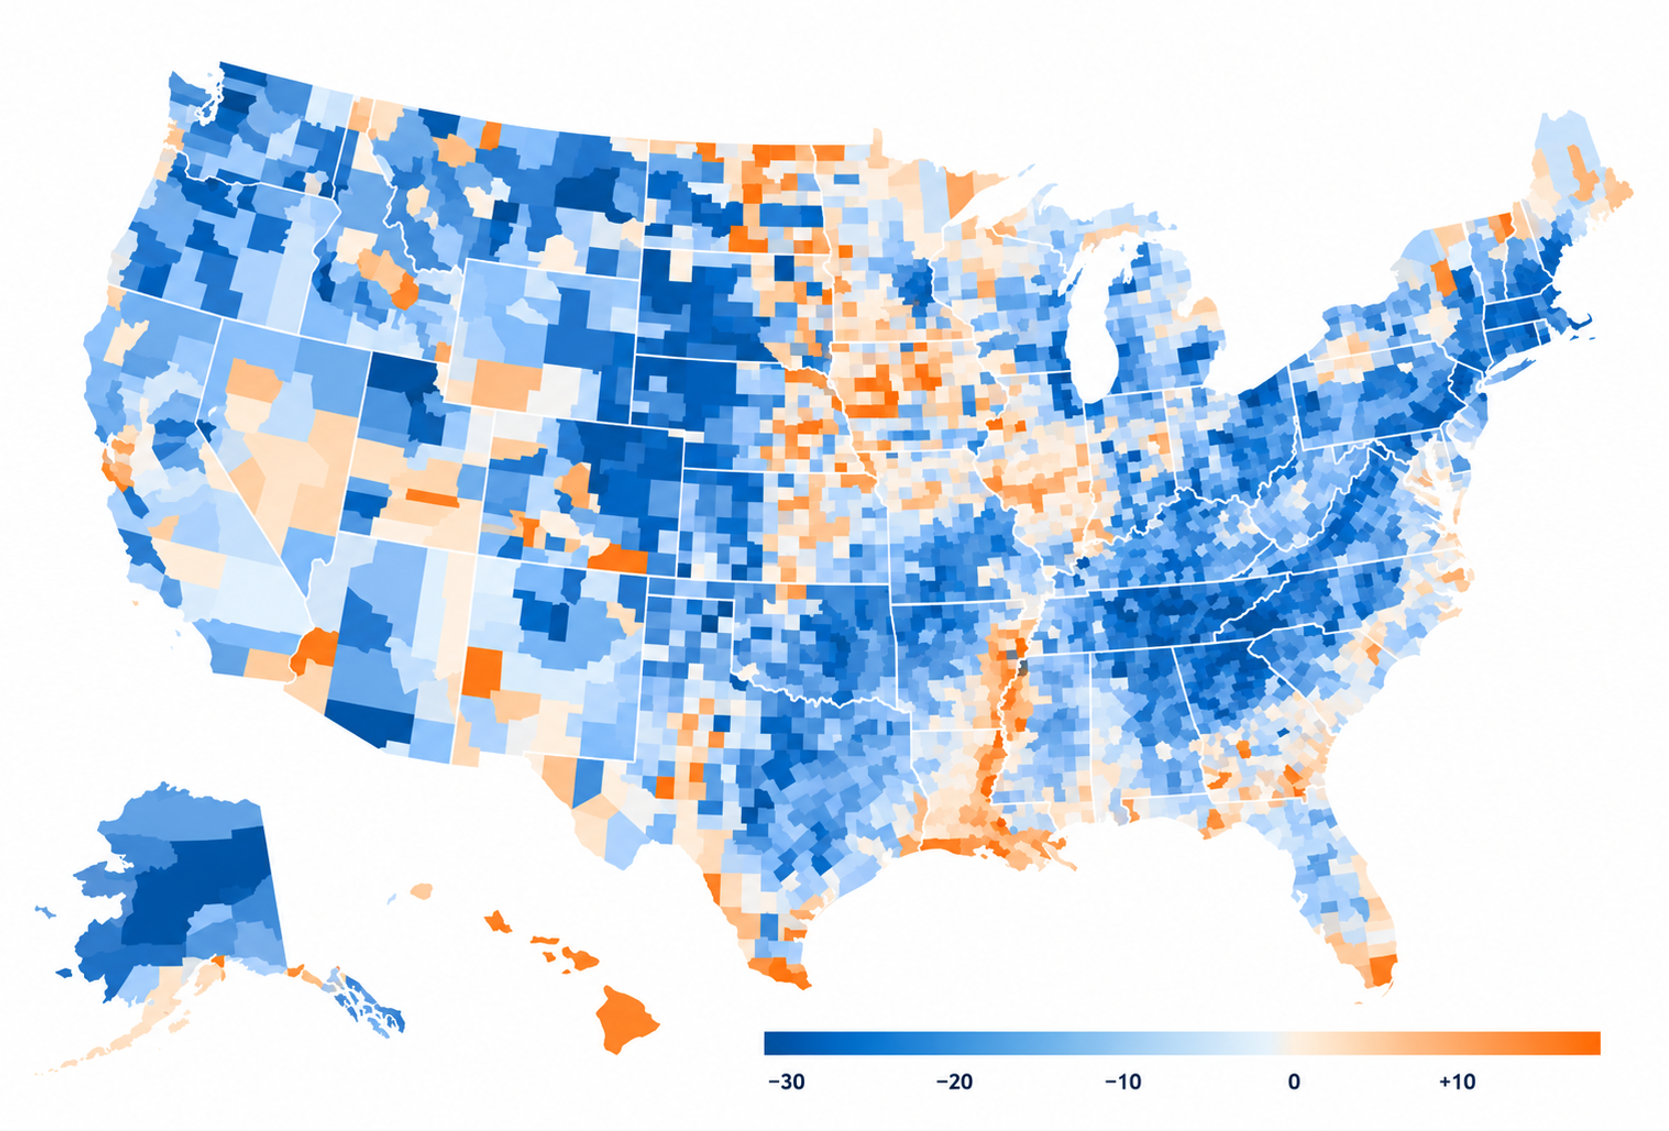
Source: Fraym. July 2026.
Will politics hinder the data center buildout?
Politicians are using data centers as a wedge issue in campaign ads and policy proposals are being reshaped to respond to voter concerns. Last month, Virginia Governor Abigail Spanberger signed an executive order that changed economic incentives and the permitting process for larger data centers.
Moreover, Texas Governor Greg Abbott, who is up for reelection in November, paused approvals for data centers seeking to connect to the ERCOT grid while regulators audit the projects. Texas and Virginia have the biggest pipeline of new data centers in the country today.
Despite political tensions, our infrastructure team expects the data center buildout to continue at pace. However, there is still risk worth monitoring, with implications for AI hardware equities like semiconductors and memory, hardware component pricing, U.S. inflation, and sovereign rates if local politics slow or nuance this important growth engine. Watch points on November 3 include the Texas Governor’s race, the Senate special election in Ohio, and data center-related ballot measures across seven states – Ohio, Illinois, Nevada, California, Wisconsin, Florida, and Kansas.
Data center pipeline: Top 10 states
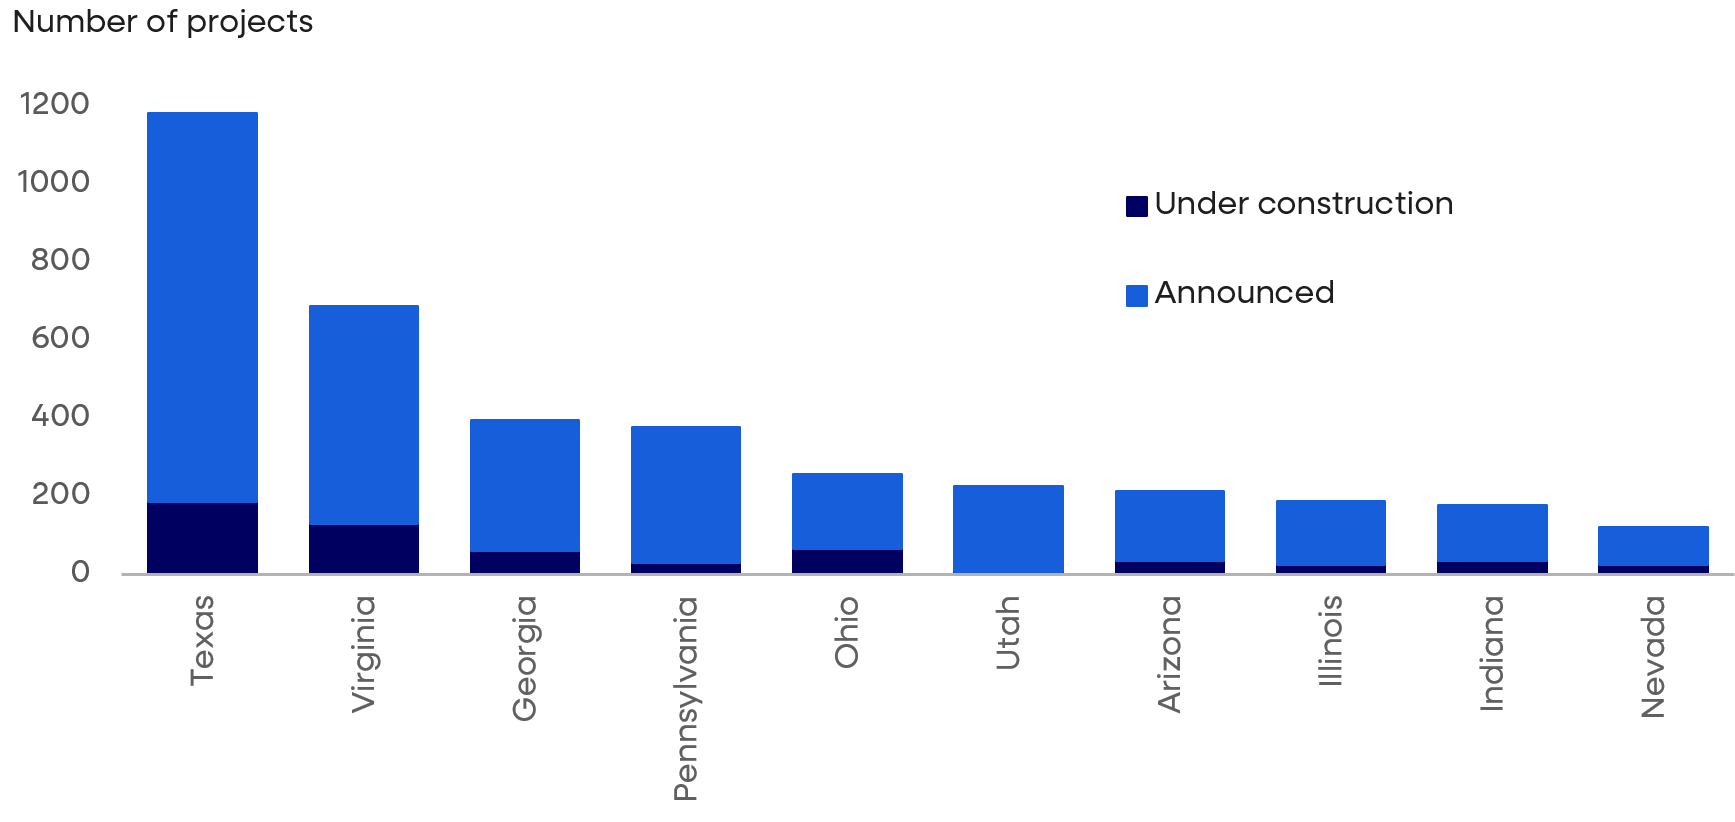
Source: Aterio, Russell Investments. Data as of October 10, 2026.
Investor implications
To date, the U.S. economy has been resilient to legislative change and we do not expect the midterm elections to shake our outlook.
A gridlocked legislature looks likely and we think the policy status quo is favorable for markets, with the S&P 500 historically rallying once the election outcome is known. Moreover, even if a midterm election surprise were to occur, we believe markets would be well-positioned to weather or even benefit from the changes.
Looking ahead to 2027, the key risks include a surprise red-wave outcome that puts further pressure on rates markets through hotter inflation, and an intensifying backlash against data centers that slows the AI buildout.
Common client questions
A divided Congress could mean policy gridlock and limited legislative change over the next two years. The article views this status quo as broadly favorable for markets and Corporate America, including because statutory tax rates are at record lows. Presidential powers over tariffs and regulation could still allow some policy changes.
A Republican sweep could bring measures such as household dividends, a federal gas tax holiday or aid for specific sectors. These could support nominal economic growth, but also keep inflation sticky and interest rates higher for longer, creating a potential risk for bond markets.
Tariffs and deregulation may be less directly affected by a change in congressional control because the president has substantial executive authority in both areas. Congress can still influence funding and appropriations, including requests related to defense, and may constrain executive actions over time.
Local concerns about electricity prices, water, noise and environmental impacts are making data centers a campaign issue. New rules, permitting changes or delays in connecting projects to power grids could slow development, with potential effects on AI hardware companies, component prices, inflation and interest rates.